ATCH VWAP Strategy
ATCHVWAPStrategy v1.0.0.0 for NinjaTrader 8 by automated-trading.ch, published 1 Nov 2026 (today). Closed source: backtest/playback free, live needs a Premium licence (nothing bought or signed up). A fully mechanical trend-pullback on a higher-timeframe RTH VWAP with every parameter and default published, plus the seller's full 226-trade MNQ 1-minute list.
Honest caveats — read first
- Published today (1 Nov 2026, v1.0.0.0). No live track record, downloaded twice at time of capture.
- Seller's own backtest, on one instrument (MNQ) and one period (2025-10-01 → 2026-10-30). The seller says it wasn't hand-picked; we can't verify that.
- No slippage modelled in their report (tick-replay fills), and their commission is $1.30/contract round trip.
- No IS/OOS split: the defaults may have been tuned on the same year the results come from. Their report also uses settings that differ from the published defaults (see contradictions C1, C3–C6, C9).
- Farm-fee re-cost: $16,791.16 net (vs $17,431.10 published) at MNQ $2.28 round trip (NT Lifetime + 1 tick per side). This is re-costed from their own trade list, not a farm run.
- Hunter 7 has no VWAP logic yet (UseVWAPBias is an empty placeholder). The +61 change request (49 new switches, default off) is with the H7 Builder. No farm backtest has been run; nothing promoted.
- The PC4 cross-check proves their trades sit on real MNQ prices at the stated minutes. It does not prove the strategy's logic generates them, or that the results will repeat.
Model
Each day a VWAP (HLC3, 15m candles by default) anchors at 09:30 ET with ±1.28σ std1 bands. On each closed chart bar a long arms when close > rising VWAP and < upper std1 (short = mirror). The trigger is the first counter candle (Immediate) or the first close beyond the prior bar's extreme (Wait For Pullback). Before entry: % change vs the HTF close N back ≥ 0.1%, trigger bar doesn't touch a std1 level, closes on the trend side of the VWAP and is still inside the band. Stop: VWAP / SuperTrend / last swing (5) / Auto (nearer of swing and std1, VWAP fallback) + offset. TP: W/L ratio (2 default) or points / $. Optional %-breakeven and SuperTrend trailing. Sizing: $-risk adjusted ($100 target, $120 max, qty 1–6). Daily stops; flat 30 s before session close.
Session clock: VWAP anchor 09:30 ET = 23:30 AEST (US summer) / 00:30 AEST (US winter). Report entries all fell 09:50–11:29 ET (23:50–01:29 / 00:50–02:29 AEST). Report exits by 16:55 ET (06:55 / 07:55 AEST).
| Label | Count |
|---|---|
| Missing | 32 |
| Partly coded | 9 |
| Coded | 6 |
| Not stated | 4 |
| Claim | 3 |
| Not needed | 1 |
| Total | 55 |
Check sequence: 1) in session → 2) daily stop not hit → 3) update HTF VWAP + bands → 4) arm → 5) trigger candle → 6) pre-entry checks (VWAP side, min % change, no std1 touch, inside band, SuperTrend filter); any fail = keep waiting → 7) stop, qty (skip if < Min Qty), TP → 8) breakeven / SuperTrend trail; flat before close.
Rules (55) — labelled against Hunter 7 +60
All VWAP rules are Missing: H7's UseVWAPBias is an empty placeholder (H7 Builder, 1 Nov 2026).
| ID | Section | Rule | Exact logic | How to test | Label vs H7 | H7 note | Source |
|---|---|---|---|---|---|---|---|
| AV-GEN-01 | General | Fully mechanical, auto strategy for NT8; one instance per instrument | No discretion; every decision from parameters | Plugin off = +60 parity; on = deterministic rerun gives identical trades | Missing | No ATCH plugin in H7 | Overview/Features |
| AV-GEN-02 | General | Execute Historical Trades toggle (backtest vs live) | Historical mode allowed when checked | n/a (platform) | Not needed | NT/H7 runs historical by default | Params 1. General |
| AV-TIM-01 | Time | Session clock time zone EST (default) / CET / Local, DST auto | Sessions interpreted in chosen zone | Unit: 09:30 EST stays 09:30 ET across DST | Coded | H7 SessionStart/End are EST | Params 2 |
| AV-TIM-02 | Time | Entries only inside Trading Sessions (default 09:30-16:00) | new entries allowed if bar close time in any window | Funnel: no entry stamped outside window; check all 226 trades ET entry ∈ 09:30-16:00 | Partly coded | H7 has one session window (SessionStart/EndHour/Minute); multi-window string missing | Params 2 |
| AV-TIM-03 | Time | Flat 30 s before session close; nothing overnight | close all at session close − 30 s | Every trade exits same day ≤ close; report shows exits 22:55 Zurich = 16:55 ET | Partly coded | H7 session_calendar flatten 16:55 ET (≈ matches report 16:55 exits) | FAQ / Features |
| AV-VWP-01 | VWAP | VWAP computed from higher-timeframe candles (15 min default) | bars per HTF candle = HTF/chartTF; non-time charts: HTF value = N bars | Unit: 15m VWAP on 1m chart equals VWAP of resampled 15m bars | Missing | H7 UseVWAPBias is an empty placeholder (H7 Builder 1 Nov) | Params 3 |
| AV-VWP-02 | VWAP | VWAP window 09:30-16:00 ET; anchors at first HTF candle inside window; stops accumulating outside | daily reset at window start | Unit: VWAP at 09:45 ET = first 15m candle typical price | Missing | none | Params 3 |
| AV-VWP-03 | VWAP | Separate long/short VWAP price source (HLC3 default; Open/High/Low/Close/HL2/OHLC4/HLCC4) | price_i per HTF candle × volume | Unit per source | Missing | none | Params 3 |
| AV-VWP-04 | VWAP | Std1 band = VWAP ± 1.28 × volume-weighted standard deviation | sigma = sqrt(Σv(p−vwap)²/Σv) | Unit vs hand calc; overlay on example images | Missing | none | Params 3 |
| AV-VWP-05 | VWAP | VWAP rising = last value > previous value (falling = <) | compare last two HTF VWAP points | Unit | Missing | none | Overview |
| AV-ARM-01 | Arm | Arm long: bar closes above rising VWAP and below upper std1, inside session | close>VWAP & VWAP rising & close<upper1 | Funnel per bar; all 101 report longs must have been armed | Missing | none | Overview |
| AV-ARM-02 | Arm | Arm short: close below falling VWAP and above lower std1 (mirror) | close<VWAP & VWAP falling & close>lower1 | Funnel; 125 report shorts | Missing | none | Overview |
| AV-ARM-03 | Arm | Arm persistence when conditions break before trigger | NOT STATED → switch AVDisarmWhenInvalid | Compare trade capture with switch on/off | Not stated | switch | — |
| AV-ARM-04 | Arm | Manual Long/Short Armed buttons (directional bias) | static enable per side | n/a | Missing | AllowLong/AllowShort may exist in host; map | Status card |
| AV-ENT-01 | Entry | Immediate mode: first pullback candle (red for long, green for short) after arm triggers entry | first bar with close<open (long) after arm | Entry minute = first counter candle after arm ±1 bar | Missing | none | Params 3 / Ex 1,4 |
| AV-ENT-02 | Entry | Wait For Pullback mode: first candle closing above previous candle high (long) / below previous low (short) | close>high[1] (long) | Switch test | Missing | none | Params 3 |
| AV-ENT-03 | Entry | Entry fill price | NOT STATED (market at bar close → next bar open assumed) | Check trade list entry prices vs 1m open of next bar | Not stated | switch AVEntryFill | — |
| AV-ENT-04 | Entry | Min Price Change %: trigger-bar close vs close of HTF candle N back ≥ +0.1% long / ≤ −0.1% short (0 = off) | (close−htfClose[N])/htfClose[N]*100 | Unit; check on reproduced trades | Missing | none | Params 3 |
| AV-ENT-05 | Entry | Price Change Lookback (VWAP points), default value not stated | 1 = last closed HTF candle | Switch {1,2} | Missing | none (default not stated) | Params 3 / Ex 1 |
| AV-ENT-06 | Entry | Pre-entry: trigger candle must not touch a std1 level | high/low of trigger bar must not reach band (which band/TF not stated) | Funnel log count of blocks | Missing | none | FAQ 'why no trade' |
| AV-ENT-07 | Entry | Pre-entry: trigger candle closes on the trend side of the VWAP | long: close>VWAP | Funnel | Missing | none | FAQ |
| AV-ENT-08 | Entry | Pre-entry: price still inside the std1 band | long: close<upper1 | Funnel | Missing | none | FAQ |
| AV-ENT-09 | Entry | SuperTrend entry filter (off default): long only while ST green, short only red, on bar just closed | trend[−1]==up | Switch test | Missing | H7 supertrend() exists only inside Greg plugin, not as entry gate | Params 3 |
| AV-ENT-10 | Entry | Blocked entry keeps waiting for next candle | setup remains armed | Funnel | Missing | none | FAQ |
| AV-ENT-11 | Entry | Daily-risk stop blocks new entries | after daily limit hit → no entries | Unit | Partly coded | H7 daily $ limits exist | FAQ |
| AV-STP-01 | Stop | VWAP stop: lower (long)/higher (short) of last two HTF VWAP values + offset | min(vwap[1],vwap[2])−off | Unit | Missing | none | Params 4 |
| AV-STP-02 | Stop | SuperTrend stop: current ST line on stop side + offset | st_line−off | Unit | Missing | indicator exists (Greg), stop mode missing | Params 4 |
| AV-STP-03 | Stop | Last Swing Point stop: last confirmed swing low/high (period 5 each side) + offset | pivot(5,5) | Implied stop vs swing on 1m | Partly coded | H7 HourStats/Sweep swing stops exist with different swing definitions | Params 4 / Ex 3,5 |
| AV-STP-04 | Stop | Auto stop: nearer of last swing and exec-TF std1 band; VWAP fallback if neither within allowed risk | internals of 'allowed risk' NOT STATED | Implied stop distance (from losers) vs both candidates | Missing | none | Params 4 / Ex 3 |
| AV-STP-05 | Stop | StopLoss Offset (points) widens every stop method | stop −/+ off | Unit | Missing | none | Params 4 |
| AV-TGT-01 | Target | TP = Win/Loss ratio × stop distance (default 2) | tp = entry ± R×ratio | Winner pts / matched loser pts ≈ ratio | Partly coded | H7 has RR-style targets in some plugins, not as a generic stop×ratio for this stop set | Params 4 |
| AV-TGT-02 | Target | Examples use 1.1:1 | CONTRADICTION C1 | Switch {2.0,1.1,1.25} | Missing | switch | Ex 1 |
| AV-TGT-03 | Target | TP Points (10 default) | tp = entry ± pts | Unit | Coded | BaselineProfitTargetPoints | Params 4 |
| AV-TGT-04 | Target | TP Currency ($200 default) | pts = $/(qty×pv) | Unit | Missing | none | Params 4 |
| AV-MGT-01 | Manage | Price breakeven at % of way to TP (+) or % of way to stop (−), −100..100 | when price reaches entry+pct×(tp−entry) move stop to entry | Example 5 (−90) replay; scratch trades in list (12 with |$|<60) | Partly coded | H7 BE is in points (Advanced_BreakEvenTriggerPoints), no % or negative trigger | Params 4 / Ex 5 |
| AV-MGT-02 | Manage | BE price offset | NOT STATED | switch AVBreakevenOffsetTicks | Not stated | switch | — |
| AV-MGT-03 | Manage | SuperTrend order management: once close ≥1 tick beyond ST line against the position, tighten stop to that bar low/high ± offset | only tightens | Unit | Missing | H7 TrailMode SuperTrend is Greg-only and trails differently | Params 4 |
| AV-STR-01 | SuperTrend | Mode ATR or Adaptive | Adaptive formula NOT STATED | n/a | Partly coded | textbook ATR mode only | Params 6 |
| AV-STR-02 | SuperTrend | Period 14, Multiplier 2.618, MA type HMA, Smooth 14 | how MA/smooth enter NOT STATED | Visual vs example images | Partly coded | H7 supertrend(atr_period,mult) no MA/smooth | Params 6 |
| AV-QTY-01 | Sizing | Quantity mode Fixed or Risk Adjusted (default) | Partly coded | H7 Fixed + RiskPercent(account %) | Params 4 | ||
| AV-QTY-02 | Sizing | Fixed Order Qty | qty = N | Unit | Coded | FixedQuantity/Contracts | Params 4 |
| AV-QTY-03 | Sizing | Risk Adjusted: qty from stop distance and Target Risk $ (100 default; report $400) | qty = TargetRisk/(stop pts×pv); rounding NOT STATED | Report: qty × loser pts × $2 ≈ $384 median (≤ $531 max) | Missing | H7 sizes by account %, not fixed $ | Params 4 / Report |
| AV-QTY-04 | Sizing | Max Allowed Risk $ (120 default) above target | accept if real risk ≤ max | Max loser $531 vs implied max $480 (+slip) | Missing | none | Params 4 |
| AV-QTY-05 | Sizing | Max Qty 6 (0 = none) | cap qty | Report qty 7/12/19 present → C3 | Missing | none | Params 4 |
| AV-QTY-06 | Sizing | Min Qty 1: calculated qty below → skip entry | skip | Unit | Missing | none | Params 4 |
| AV-DAY-01 | Daily | Stop @ daily profit $ | stop new entries | Unit | Coded | UseDailyProfitTarget | Params 5 |
| AV-DAY-02 | Daily | Stop @ daily loss $ | stop new entries | Unit | Coded | UseDailyLossLimit | Params 5 |
| AV-DAY-03 | Daily | Stop @ daily winning count | Unit | Missing | none | Params 5 | |
| AV-DAY-04 | Daily | Stop @ daily losing count | Unit | Missing | none | Params 5 | |
| AV-DAY-05 | Daily | Stop @ daily trades count | Unit; report max trades/day | Coded | Advanced_MaxTradesPerDay | Params 5 | |
| AV-CLM-01 | Claim | MNQ 1m $400 risk 2025-10-01→2026-10-30: 226 trades, net $17,431.10, PF 1.48, DD −$2,262.20, 54.4% win, NT Lifetime commissions | claim; trade list published | Recompute from list (done: sums match); farm rerun after +61 | Claim | — | Performance report |
| AV-CLM-02 | Claim | Tick-level fills, '99% conformant' backtests | claim | Compare farm 1m vs their fills | Claim | — | Features |
| AV-CLM-03 | Claim | Backtest period not hand-picked | claim | n/a | Claim | — | Performance report |
| AV-TIM-05 | Time | Report evidence: all 226 entries 09:50-11:29 ET although default session is 09:30-16:00 | CONTRADICTION C9 → switch sessions {09:30-16:00, 09:30-11:30} | Reproduce trade list with each; count entries after 11:30 | Not stated | switch | Trade list |
| AV-VWP-06 | VWAP | Report evidence: earliest entry 09:50 ET fits HTF 10m (Example 1 uses 10m) not 15m default | CONTRADICTION C5 → switch HTF {15,10} | Reproduce with each | Missing | switch | Trade list / Ex 1 |
ATCH VWAP pullback locked rules template one — A+ checklist (draft for David)
- In trading session (09:30–16:00 ET default; report evidence 09:30–11:30)
- HTF VWAP rising (long) / falling (short), last vs previous point
- Close above VWAP and below upper std1 (long) — mirror short
- First counter candle (Immediate) or close beyond prior extreme (Wait For Pullback)
- Price change vs HTF close N back ≥ Min % (0.1 default; 0.15 in examples)
- Trigger candle doesn't touch a std1 level; closes on the trend side; still inside band
- Stop by chosen mode + offset; qty from $ risk within max risk, Min ≤ qty ≤ Max
- TP = W/L ratio × stop (2 default; 1.1 in examples)
- Optional breakeven (Example 5: −90%) and SuperTrend trail
- Flat 30 s before session close; daily stops respected
Contradictions and unknowns (switchable, unresolved)
- C1 W/L ratio 2 (default) vs 1.1 (Ex 1) vs ~1.26 (report: median winner 86.25 pts / median loser 68.25 pts)
- C2 Breakeven −90% in Ex 5 vs off by default
- C3 Max Qty 6 vs report quantities 7, 12 and 19
- C4 Target risk $100 default vs the "$400 risk" report
- C5 HTF 15m default vs 10m in Ex 1; earliest report entry 09:50 ET fits 10m
- C6 Min price change 0.1% vs 0.15% in Ex 1/4
- C7 Price-change lookback default not stated vs "two VWAPs before" (Ex 1)
- C8 Stop-mode default not stated (examples show std1, swing, swing)
- C9 Sessions 09:30–16:00 default vs all 226 report entries in 09:50–11:29 ET
- Unknowns U1–U10: intrabar VWAP, disarm rule, WFP needs counter candle, "touch std1", Auto "allowed risk", exec-TF band, BE offset, Adaptive SuperTrend, SuperTrend MA/smooth use, qty rounding.
A+ examples (seller's chart images)
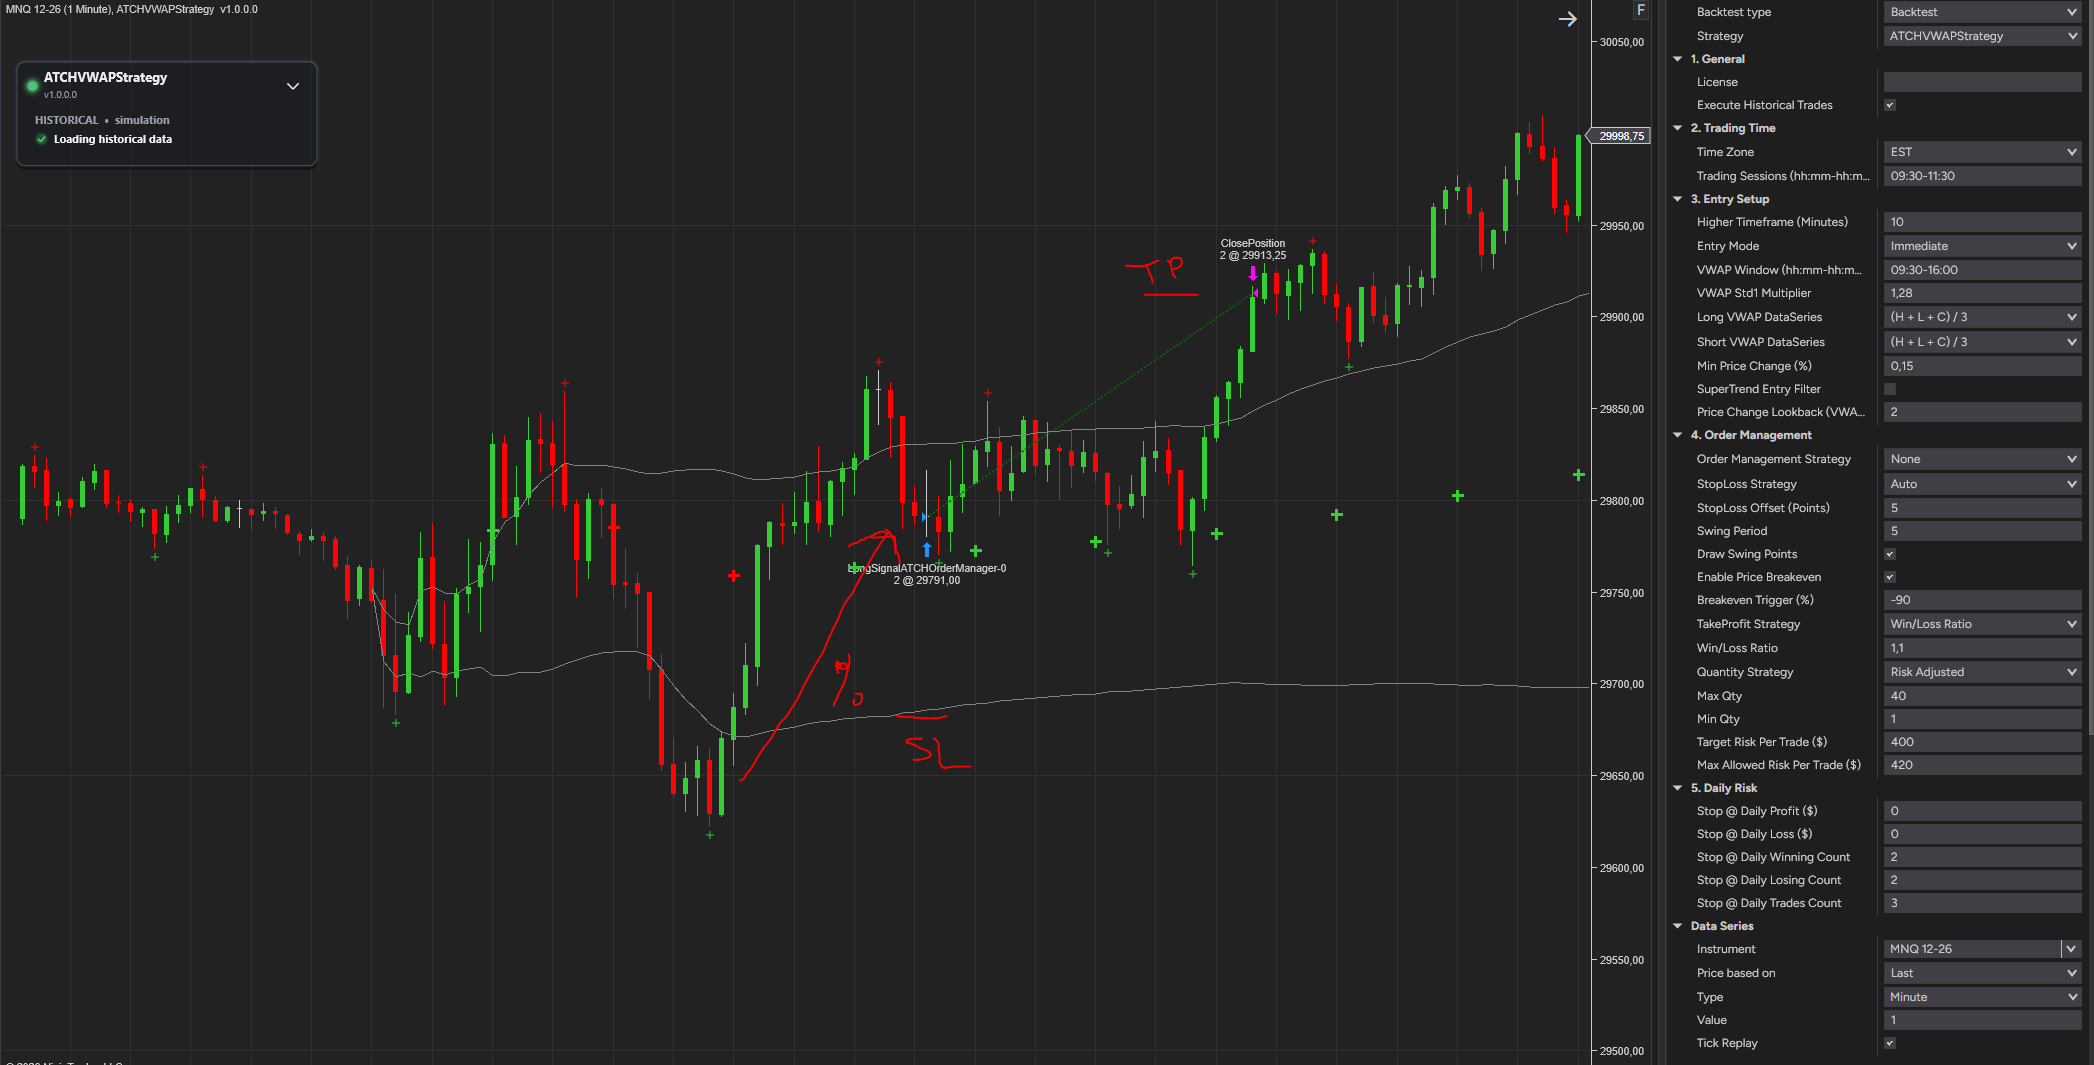
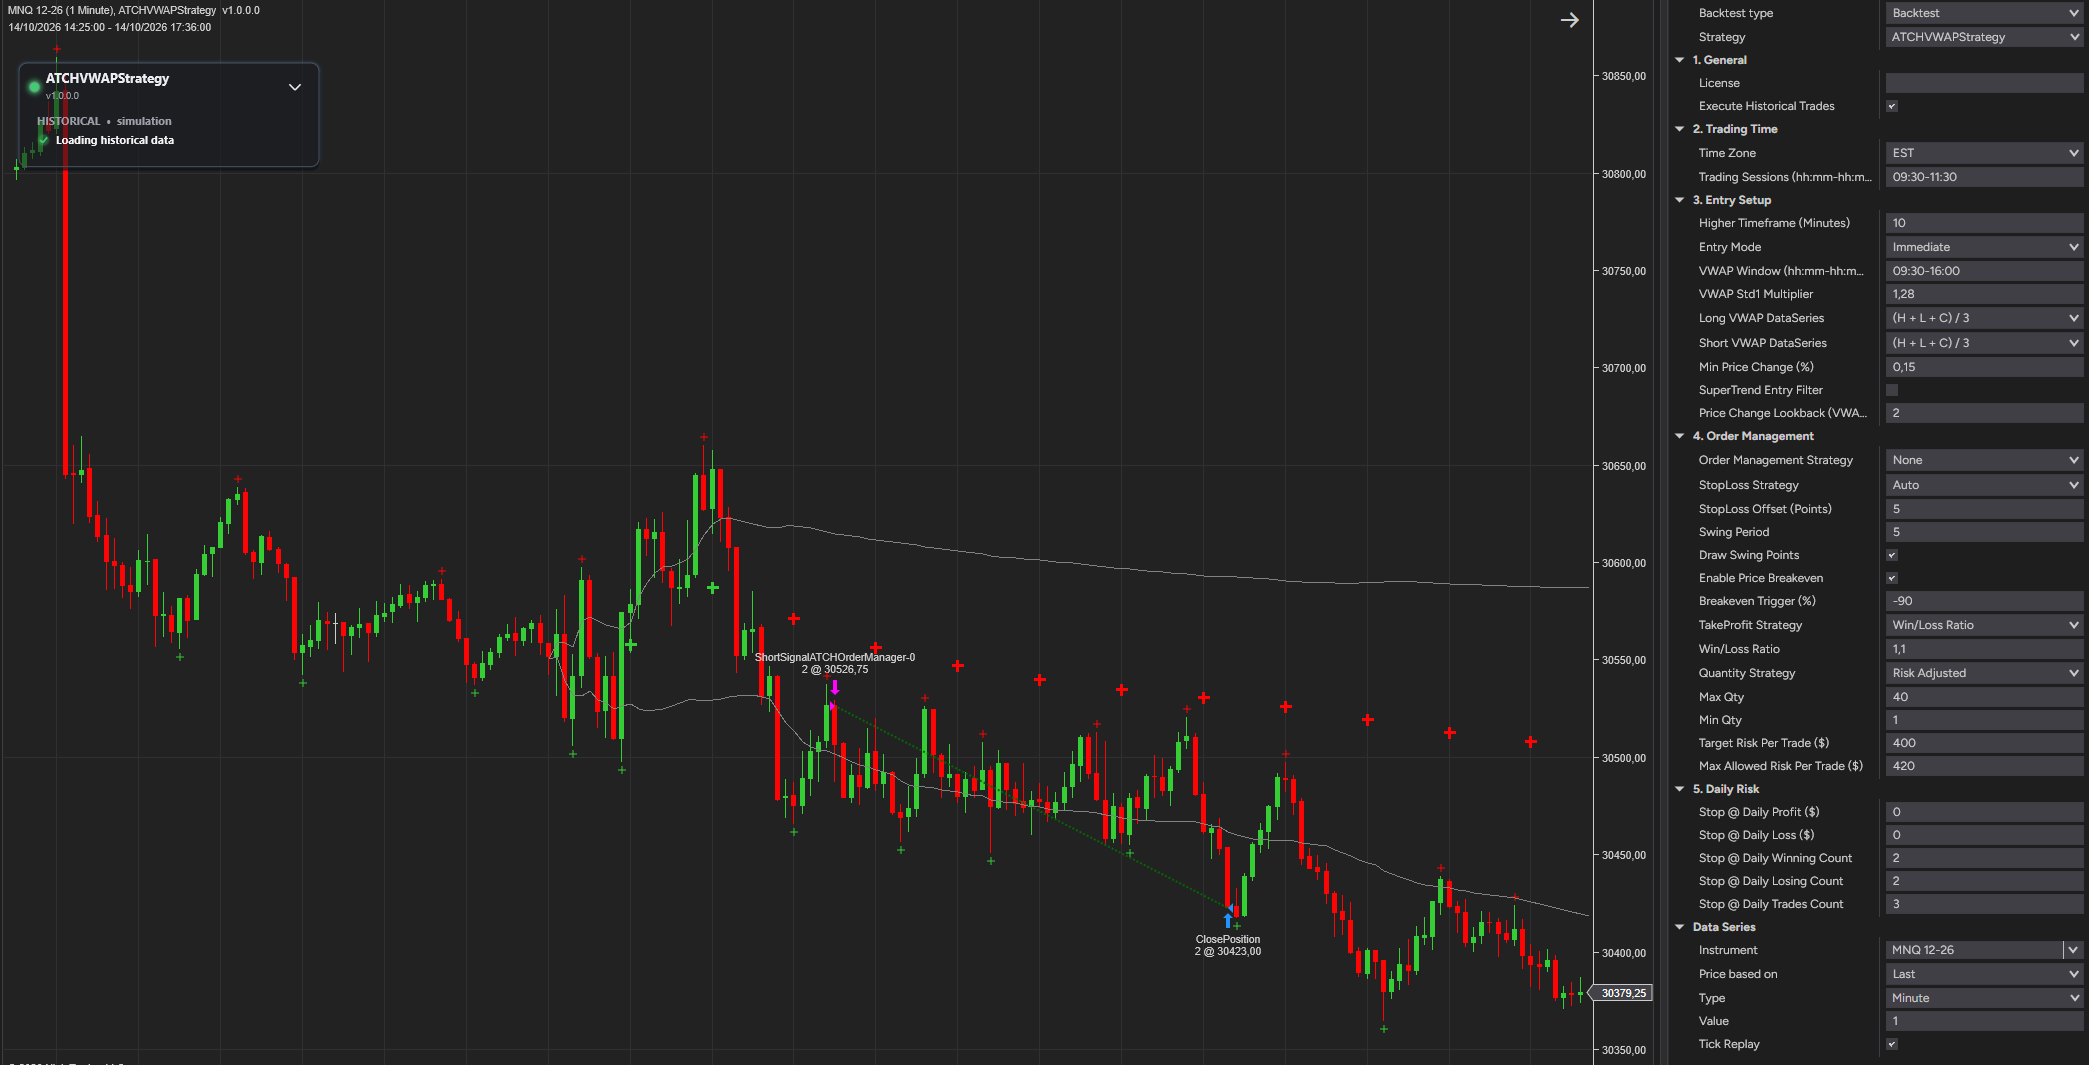
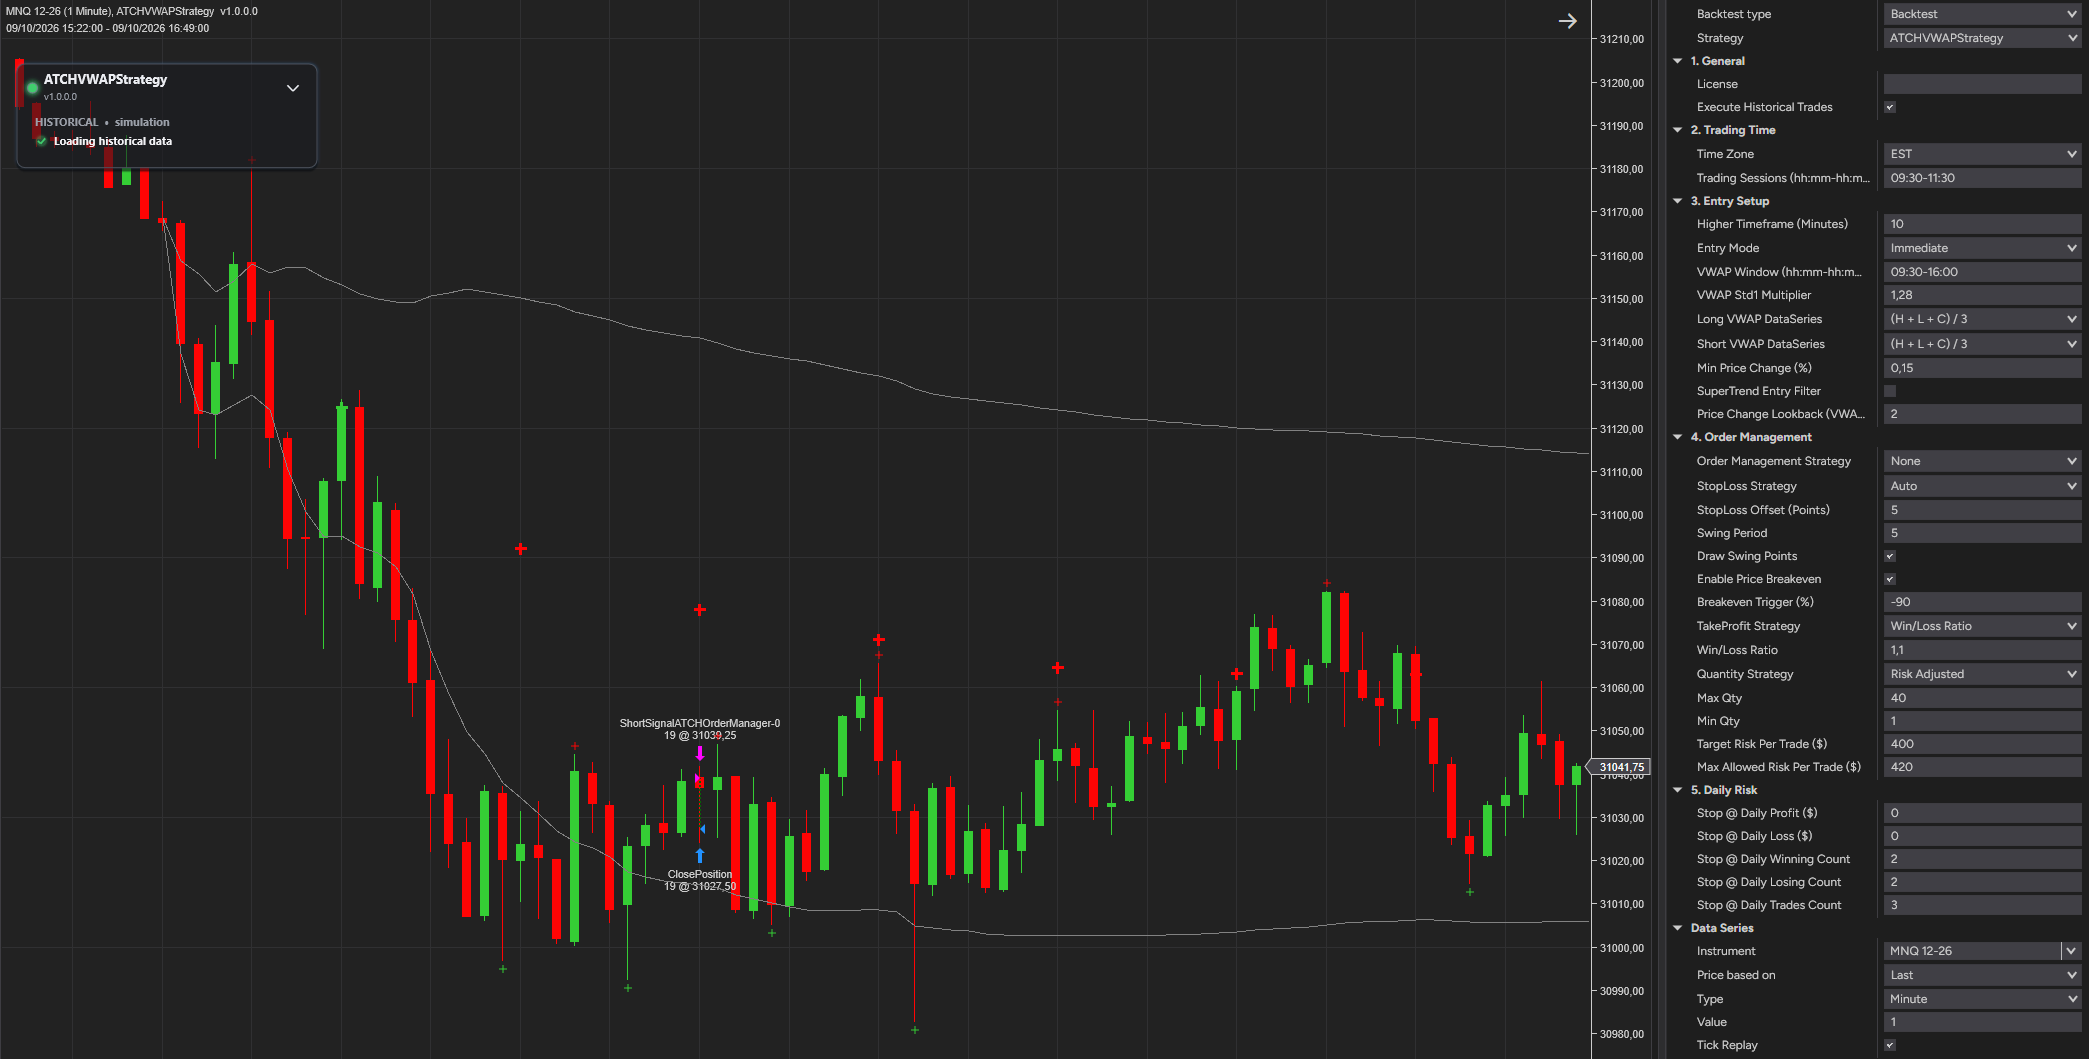
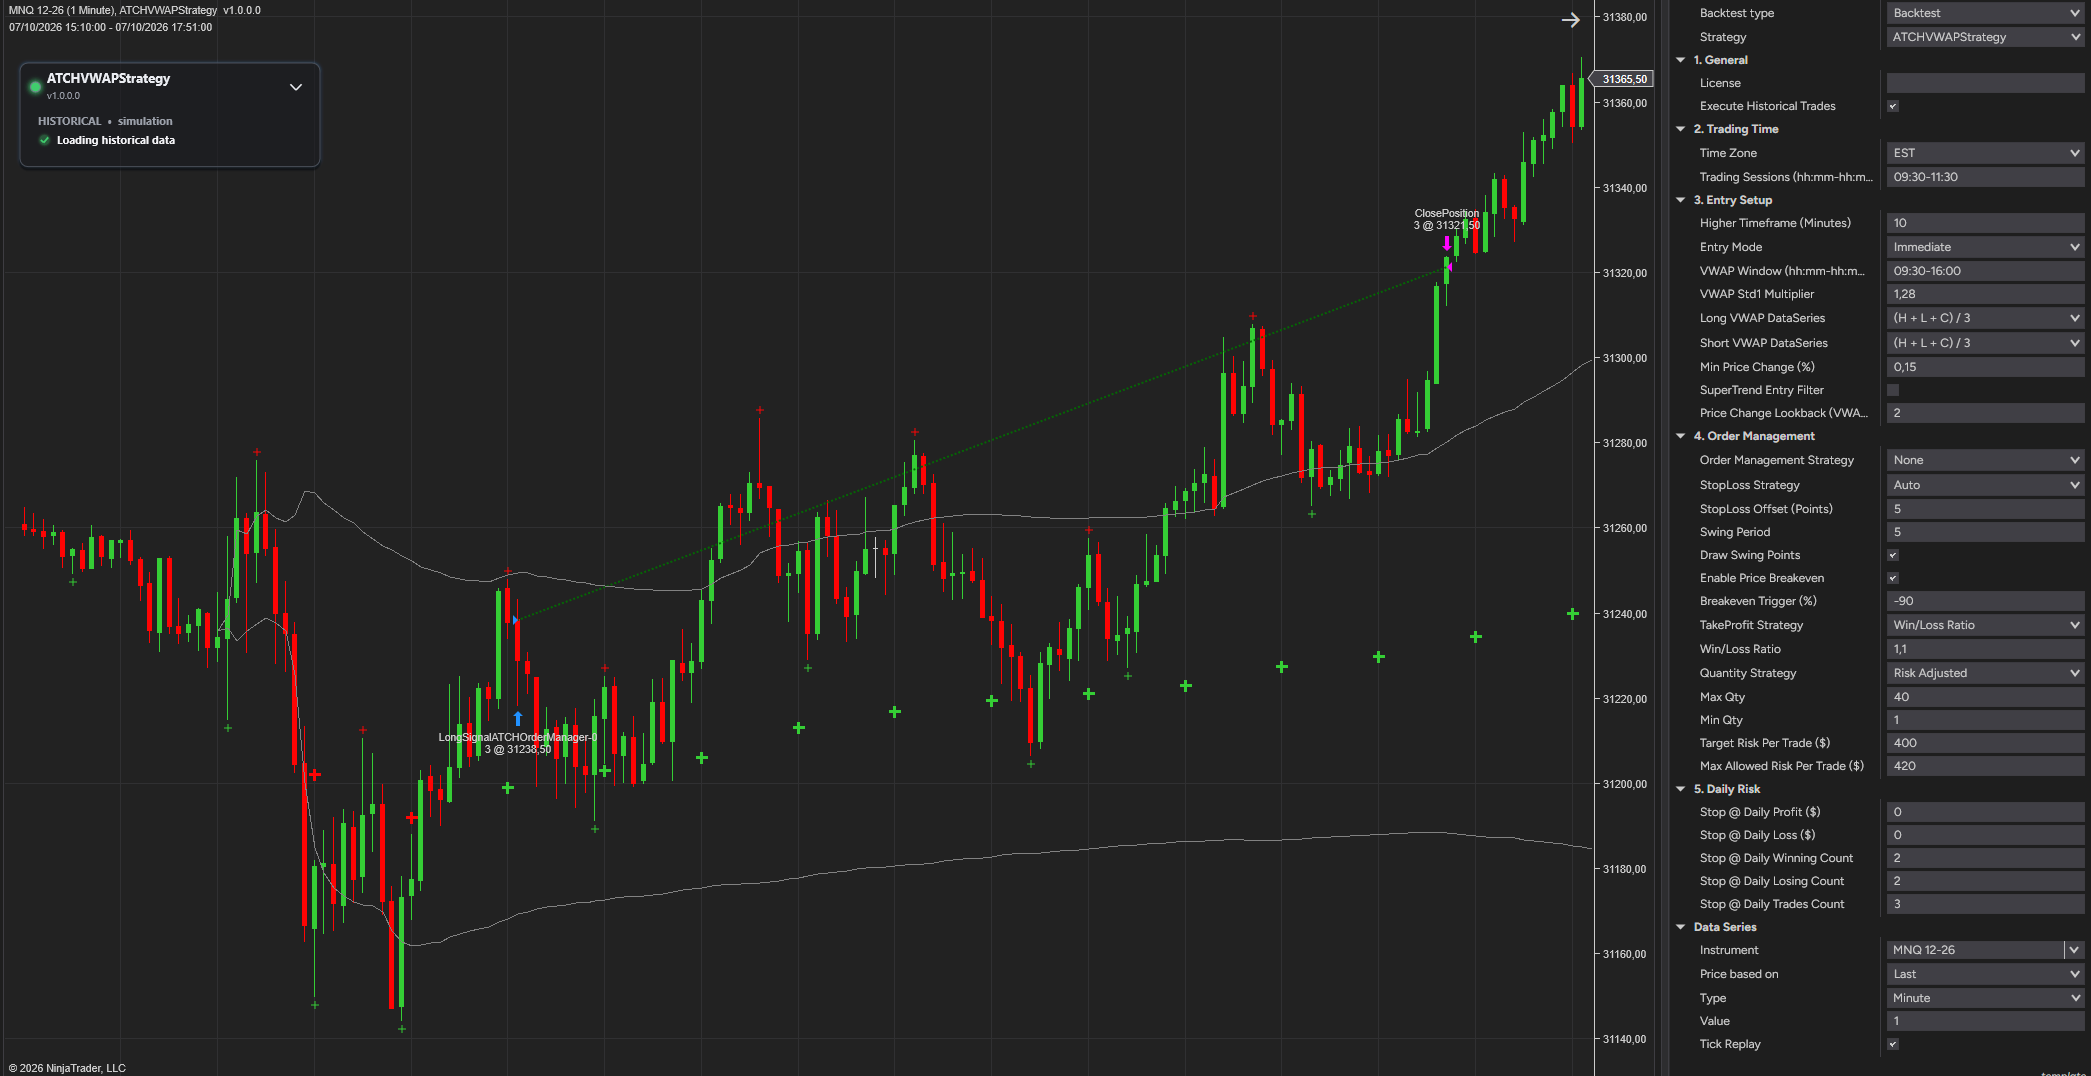
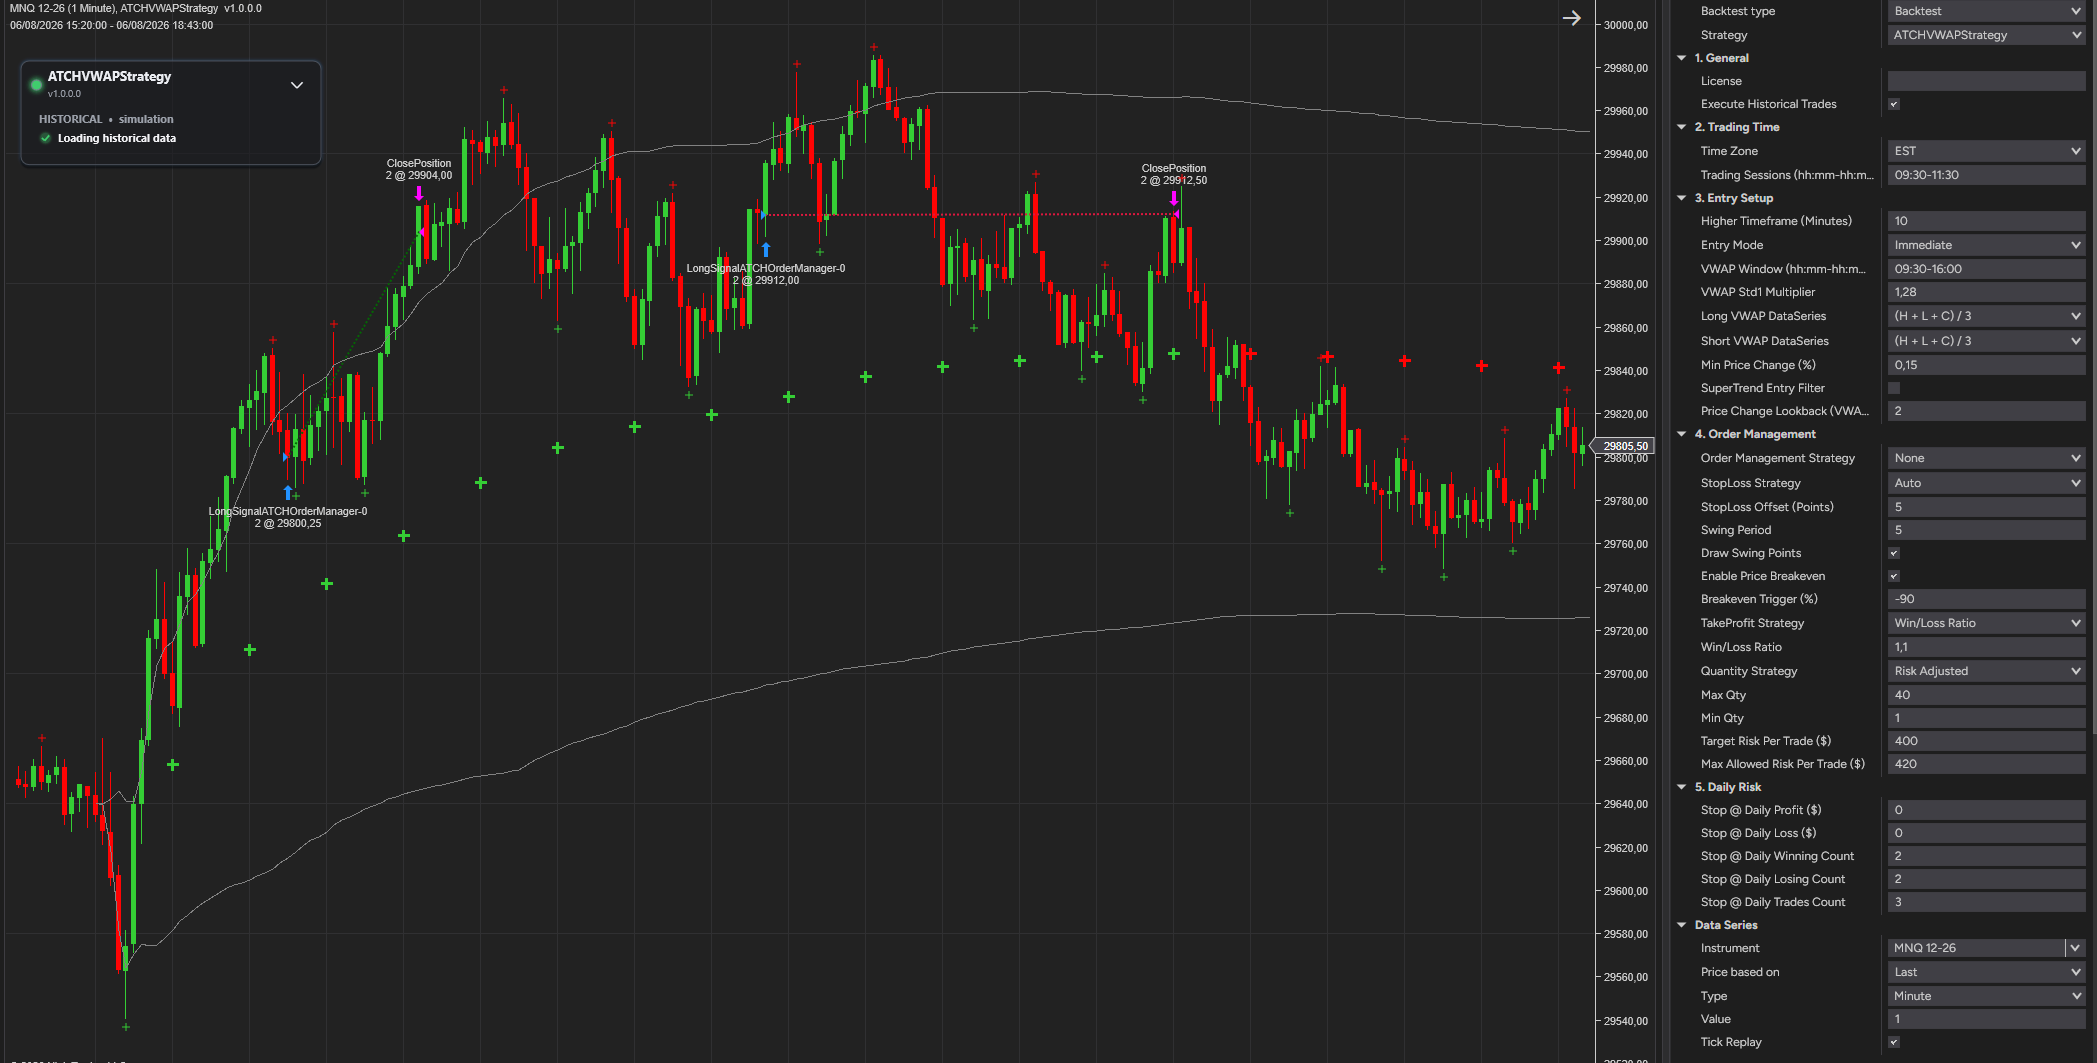
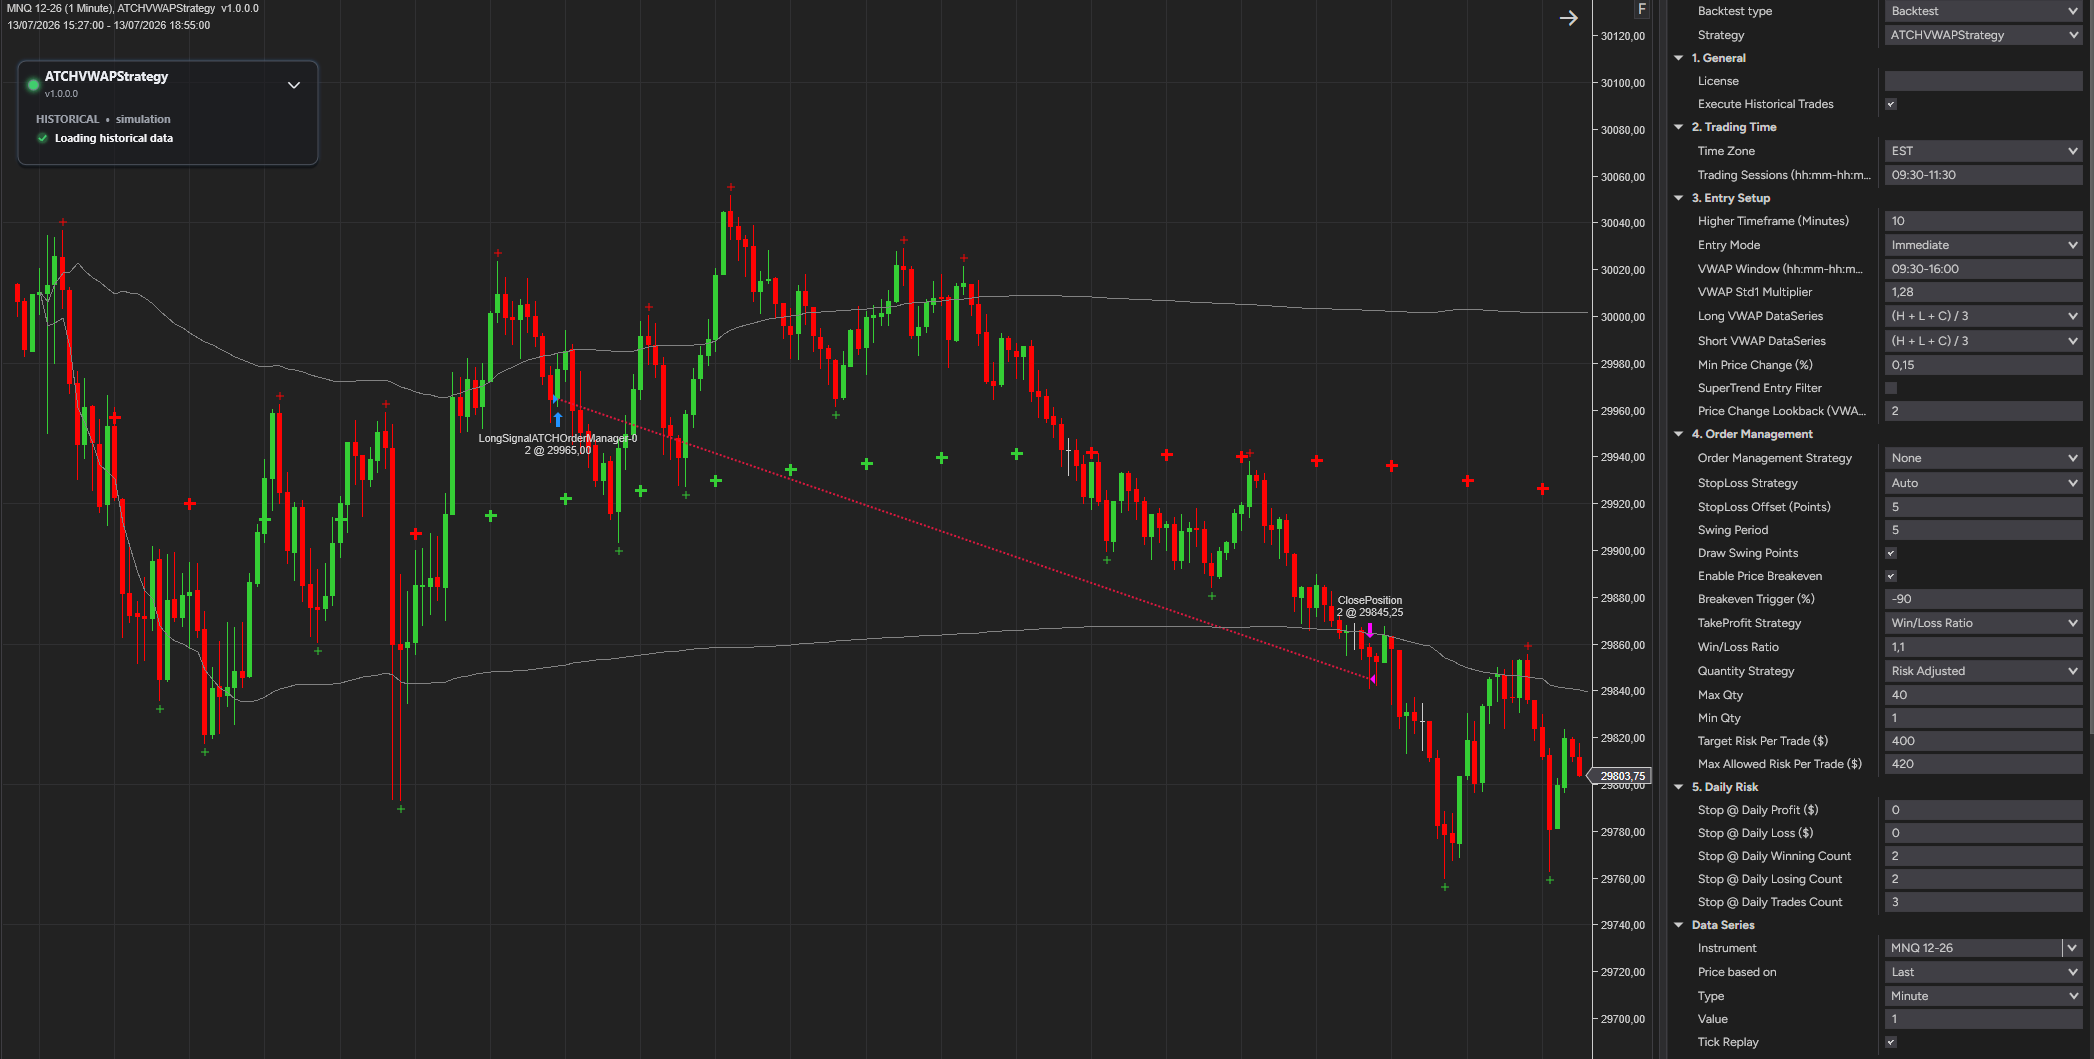
Trade list (226) — seller's backtest, captured in full
Time zone: the list is in Europe/Zurich time (page script pfReportTimezone; all 226 match their chart API's UTC timestamps to the minute after conversion). Zurich − ET = 6 h, except 20 trades in the DST-gap weeks (late Oct and March), where it's 5 h. Every row has ET and UTC times, entry and exit price, qty, P&L and commission. Stops are filled for 89 full-size losers and targets for 119 full-size winners (their exit prices); the other rows carry the stop-distance range implied by $400 sizing.
As published: 226 trades · net $17,431.10 · PF 1.48 · win 54.4% · max DD $-2,262.20 · avg $77.13
Re-costed at farm fee $2.28 RT: 226 trades · net $16,791.16 · PF 1.46 · win 54.4% · max DD $-2,285.72 · avg $74.30 (from their list, not a farm run)
Long (farm fee): 101 trades · net $11,131.96 · PF 1.75 · win 59.4% · max DD $-1,656.70 · avg $110.22
Short (farm fee): 125 trades · net $5,659.20 · PF 1.26 · win 50.4% · max DD $-2,873.30 · avg $45.27
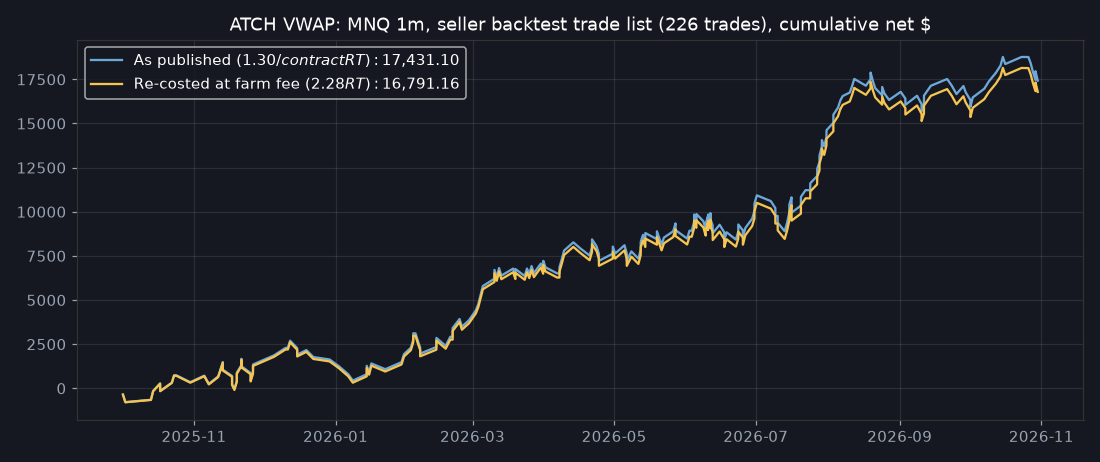
| Month (ET) | Trades | Net as published | Net at farm fee |
|---|---|---|---|
| 2025-10 | 10 | $347.50 | $318.10 |
| 2025-11 | 18 | $1,000.10 | $948.16 |
| 2025-12 | 10 | $285.30 | $256.88 |
| 2026-01 | 10 | $301.00 | $276.50 |
| 2026-02 | 16 | $1,917.20 | $1,877.02 |
| 2026-03 | 20 | $3,369.20 | $3,314.32 |
| 2026-04 | 16 | $805.20 | $750.32 |
| 2026-05 | 19 | $930.80 | $882.78 |
| 2026-06 | 31 | $1,510.40 | $1,420.24 |
| 2026-07 | 27 | $4,154.20 | $4,094.42 |
| 2026-08 | 19 | $1,713.20 | $1,658.32 |
| 2026-09 | 14 | $436.30 | $393.18 |
| 2026-10 | 16 | $660.70 | $600.92 |
PC4 1-minute cross-check — 185 trades checked, 175 inside the bar on both entry and exit
Run on PC4 with a script (F:\trader_packs\ATCH_VWAP\scripts\atch_crosscheck.py) against PC4's NinjaTrader MNQ 1-minute export (UTC, bar-end stamps). Every 2026 trade was checked: 185. The 41 trades from Oct–Dec 2025 can't be checked because PC4 has no MNQ 12-25 data. Their prices are a back-adjusted "MNQ 12-26" series. One constant offset per contract fits every trade:
| PC4 contract | Roll offset (report − actual) | Trades | Entry and exit inside 1m bar (±0.30 pt) |
|---|---|---|---|
| MNQ 03-26 | +809.25 | 35 | 33 |
| MNQ 06-26 | +595.00 | 59 | 55 |
| MNQ 09-26 | +299.00 | 70 | 67 |
| MNQ 12-26 | −0.75 | 21 | 20 |
Result: entries 181/185, exits 179/185, both 175/185. The 10 misses are all within 0.45–0.55 pt (about 2 ticks) of the bar's range. That's consistent with PC4's export rounding prices to 0.1 and a ~0.75-pt basis between their feed and PC4's on the 12-26 contract. Caveat: 1-minute bars are often 20–60 pts wide, so landing inside a bar is a loose test on its own. The strong evidence is that one fixed offset per contract fits all 185 trades. A sample of 21 rows:
| # | PC4 contract | Side | Entry ET | Report entry | Roll offset | Actual entry | 1m bar low | 1m bar high | Actual exit | Exit bar low | Exit bar high | Both inside bar |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 39 | 03-26 | Long | 2026-01-02 09:54 | 26553.5 | 809.25 | 25744.25 | 25735.0 | 25758.2 | 25649.75 | 25625.0 | 25668.0 | True |
| 48 | 03-26 | Short | 2026-01-30 11:03 | 26656.25 | 809.25 | 25847.0 | 25835.8 | 25850.0 | 25771.0 | 25754.5 | 25790.8 | True |
| 57 | 03-26 | Long | 2026-02-13 10:20 | 25563.0 | 809.25 | 24753.75 | 24743.8 | 24811.0 | 24840.0 | 24806.8 | 24845.8 | True |
| 66 | 03-26 | Long | 2026-03-03 11:11 | 25372.75 | 809.25 | 24563.5 | 24544.0 | 24564.2 | 24653.0 | 24622.5 | 24653.0 | True |
| 75 | 06-26 | Short | 2026-03-19 10:30 | 25021.75 | 595.0 | 24426.75 | 24422.2 | 24440.0 | 24521.75 | 24510.0 | 24540.5 | True |
| 84 | 06-26 | Long | 2026-03-31 11:20 | 24129.5 | 595.0 | 23534.5 | 23501.2 | 23534.8 | 23660.75 | 23609.2 | 23670.5 | True |
| 93 | 06-26 | Long | 2026-04-20 10:02 | 27371.25 | 595.0 | 26776.25 | 26741.0 | 26777.0 | 26736.25 | 26734.2 | 26756.0 | True |
| 102 | 06-26 | Long | 2026-05-05 10:39 | 28693.75 | 595.0 | 28098.75 | 28092.2 | 28100.0 | 28177.0 | 28164.8 | 28177.0 | True |
| 111 | 06-26 | Long | 2026-05-14 10:22 | 30237.5 | 595.0 | 29642.5 | 29628.8 | 29664.8 | 29763.5 | 29744.0 | 29768.2 | True |
| 120 | 06-26 | Short | 2026-06-01 10:09 | 30966.25 | 595.0 | 30371.25 | 30362.0 | 30384.0 | 30449.5 | 30432.0 | 30449.8 | True |
| 129 | 06-26 | Short | 2026-06-09 10:26 | 30104.0 | 595.0 | 29509.0 | 29461.5 | 29521.5 | 29344.75 | 29337.0 | 29411.5 | True |
| 141 | 09-26 | Long | 2026-06-18 10:15 | 30822.25 | 299.0 | 30523.25 | 30500.0 | 30536.2 | 30634.0 | 30620.8 | 30643.0 | True |
| 150 | 09-26 | Long | 2026-06-30 10:10 | 30633.75 | 299.0 | 30334.75 | 30305.8 | 30346.5 | 30406.0 | 30394.8 | 30418.5 | True |
| 159 | 09-26 | Short | 2026-07-15 09:58 | 30104.75 | 299.0 | 29805.75 | 29790.5 | 29819.8 | 29659.5 | 29655.0 | 29710.5 | True |
| 168 | 09-26 | Long | 2026-07-24 11:23 | 28797.5 | 299.0 | 28498.5 | 28496.0 | 28525.0 | 28598.0 | 28585.0 | 28599.2 | True |
| 177 | 09-26 | Short | 2026-07-31 11:19 | 28557.75 | 299.0 | 28258.75 | 28251.2 | 28273.0 | 28160.25 | 28132.0 | 28187.8 | True |
| 186 | 09-26 | Short | 2026-08-12 10:02 | 30203.0 | 299.0 | 29904.0 | 29870.0 | 29903.5 | 29852.0 | 29848.2 | 29895.2 | 0.5 pt off (entry) |
| 195 | 09-26 | Long | 2026-08-25 09:54 | 29660.75 | 299.0 | 29361.75 | 29335.5 | 29366.0 | 29316.25 | 29305.2 | 29345.2 | True |
| 204 | 09-26 | Short | 2026-09-11 10:41 | 29694.75 | 299.0 | 29395.75 | 29383.8 | 29401.8 | 29338.25 | 29334.0 | 29393.8 | True |
| 213 | 12-26 | Short | 2026-10-02 11:02 | 31179.25 | -0.75 | 31180.0 | 31148.8 | 31179.8 | 31092.0 | 31085.0 | 31121.2 | True |
| 222 | 12-26 | Short | 2026-10-27 09:59 | 29571.25 | -0.75 | 29572.0 | 29560.5 | 29582.2 | 29660.5 | 29626.8 | 29668.5 | True |
Hunter 7 status
The +61 change request (plugin AV_VWAP, 49 switches, all default off, plus the test plan: parity → reproduction gate on the 226 trades → same period at farm fees → IS/OOS/hold-out → equity curves → Stage One instruments) was sent to the All_Hunter_7 Builder by David on 1 Nov 2026. This lane does not edit H7 code. No farm results yet.
Claims log (claims, not facts)
- MNQ 1m $400 risk: 226 trades, net $17,431.10, PF 1.48, max DD −$2,262.20, 54.4% win. The totals recompute exactly from their list; the strategy itself isn't verified by a farm run.
- "Intraday tick-level backtesting ... 99% conformant to real-time".
- "The backtest period wasn't hand-picked."
Data-gap note
- PC4 MNQ 1m covers 1 Jan → 30 Oct 2026 (contracts 03-26, 06-26, 09-26, 12-26). Oct–Dec 2025 (41 trades) isn't covered — affects results: yes, those trades are unchecked.
- Their prices are back-adjusted to MNQ 12-26; offsets were derived per contract (above) — possibly (a constant ~0.75-pt basis remains).
- PC4's export rounds prices to 0.1 pt; tolerance ±0.30 pt — possibly (accounts for the 10 two-tick misses).
- Their fills are tick-replay; farm bars are 1-minute, so stop-vs-target order inside one bar isn't resolved — possibly, for later farm runs.
- Their chart API returned no OHLC bars, only trade times; prices were checked against PC4 data only.
Pack
PC4 F:\trader_packs\ATCH_VWAP\: master rules, rules CSV, 226-trade CSV (raw + converted), PC4 cross-check CSV and summary, summary JSON, chart-API JSON, H7 change request v61, source page, images, script. sha256 list in SHA256SUMS.txt.